Agentcraft®

Employee experience · Preview

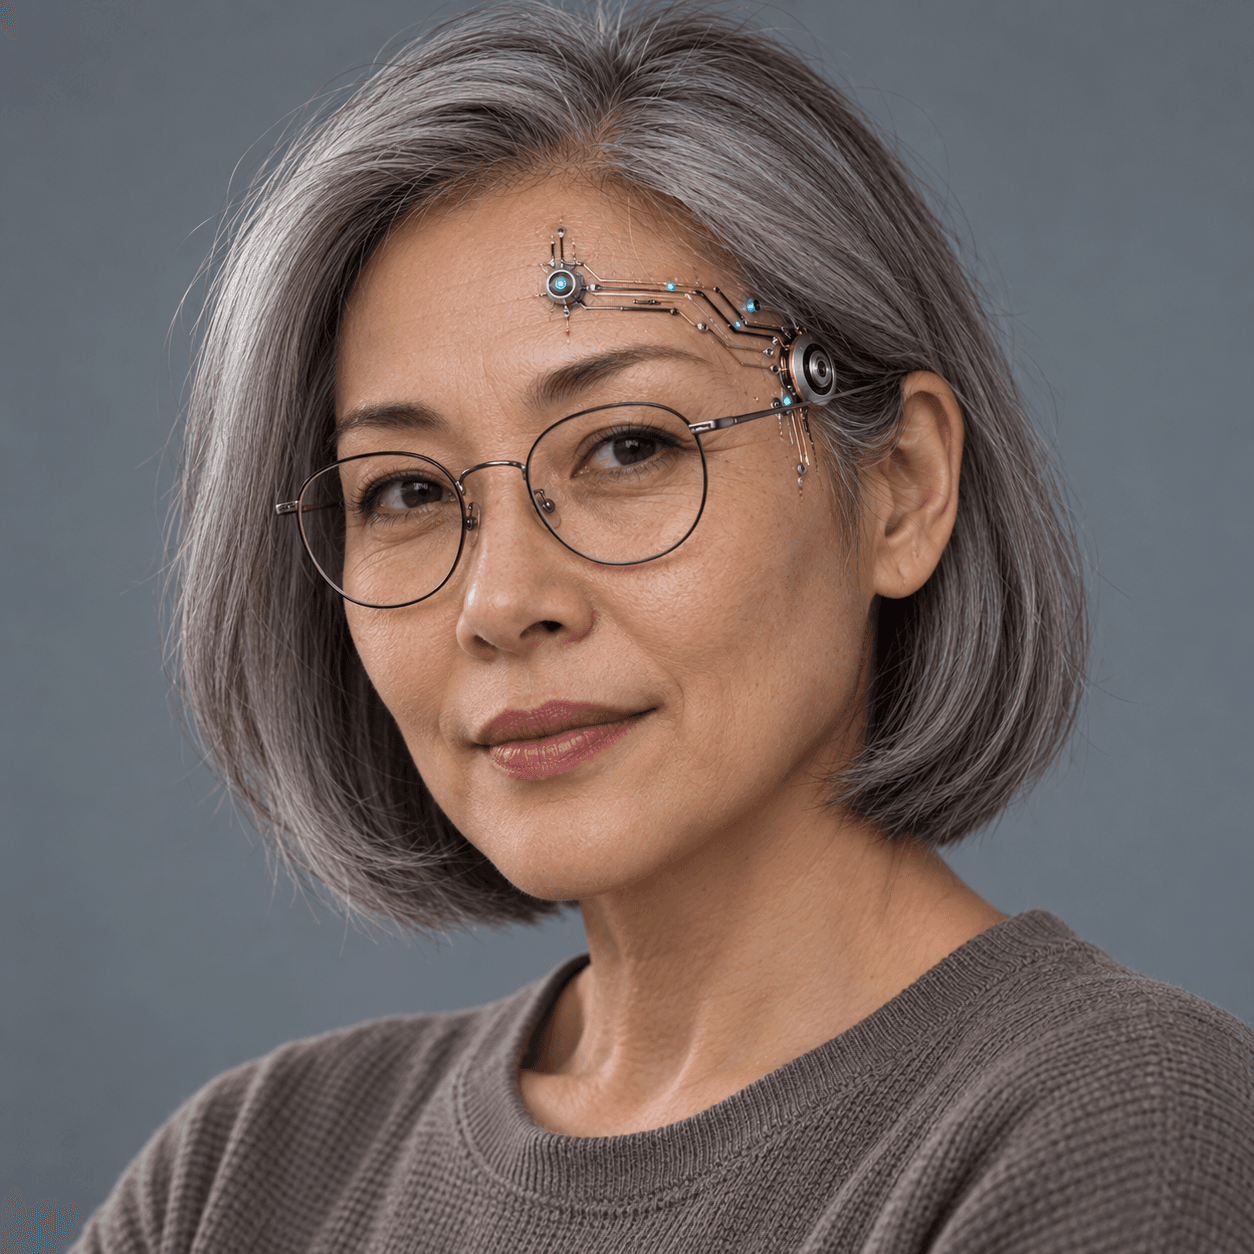
AuditorYour company’s inspector. Finds gaps before they become findings.

Reviews regulatory compliance, KVKK and financial consistency. Identifies missing procedures and verifies implementation. Brings gaps to the CEO and follows them through to evidence-backed closure.

Auditor
Agentcraft®Auditor

Your company’s general inspector

Knows your controls. Keeps findings in view.

Carries audit scope, past findings and accepted closure evidence into the next review. You manage what it remembers.

Share the rules and how work actually happens

Bring together your operating scope, policies, financial records and personal-data processes. Auditor compares documented rules with evidence from daily operations.

LEARNS FROM YOUR WORK
My AuditorLearns from working with you

“We agreed not to close a finding until implementation evidence has been reviewed. Shall I keep that rule for future audits?”

Example conversation. Your choice is only used in this preview.

A conversation is enough

Ready-to-use task examples

Ask about audit readiness, KVKK practices, financial consistency or missing procedures. Your Auditor answers with findings, supporting evidence and unresolved questions.

Assess external audit readiness

CEO

I need to organize preparation for the external audit. Show evidenced controls, gaps and the owners or decisions needed first.

My Auditor

The reviewed controls have mixed evidence: some are documented and operating, while others lack implementation records. I would prioritize missing ownership and evidence before calling the review complete.

Inspection readiness · Evidence overview

  • Evidenced · The sampled invoice reconciliations have source references and reviewer records.
  • Missing · Two procedures have no assigned owner or recent implementation sample.
  • First priority · CEO assigns owners and evidence deadlines; this review does not certify overall compliance.

Review the new data flow for KVKK compliance

Software Architect

I added a customer support integration to the design. Compare its personal-data flow with our inventory, notices and verified requirements; show missing evidence and questions for specialist review.

My Auditor

The shared records contain a data flow missing from the inventory and no implementation evidence for one retention rule. These are review gaps; legal applicability still needs the responsible specialist’s assessment.

KVKK review · Documentation and practice

  • Inventory · A new customer support integration is present in process notes but not in the data inventory.
  • Retention · A retention rule is documented, but no sample execution or exception record was supplied.
  • Follow-up · Confirm scope with the legal specialist and ask the process owner for supporting records.

Do our financial records match?

You

Compare this month’s invoices, payment transactions and accounting records. Explain discrepancies and what needs verification without changing the records.

My Auditor

I matched the shared records by reference, currency and period. Two exceptions require finance-owner review; I have not treated them as confirmed accounting errors yet.

Financial verification · Exceptions

  • Possible duplicate · The same invoice reference appears twice in the expense register.
  • Unmatched transaction · One payment has no entry in the supplied ledger; check timing and missing exports.
  • Verification · Finance owner explains or corrects the exceptions; Auditor checks the source-linked reconciliation evidence.

Which regulatory changes concern us?

You

Review current official sources for our documented countries and activities. Separate relevant changes from items whose applicability needs specialist confirmation.

My Auditor

I structured the review by jurisdiction, activity and source date. The sample report separates confirmed scope from open applicability questions instead of treating every publication as a new obligation.

Regulatory review · Scope and sources

  • Source record · Official publication, publication date, effective date where stated and the affected activity.
  • Applicability · Record the company facts supporting inclusion; mark unresolved interpretation for the legal specialist.
  • Action proposal · For confirmed requirements, map existing controls, missing evidence and the owner the CEO needs to assign.

Which procedures are missing or not applied?

You

Review our privacy and data-sharing procedures. Which are missing, which exist only on paper and what organization should the CEO put in place?

My Auditor

The procedure set needs clearer ownership and implementation records. I separated document gaps from technical evidence that needs Cybersecurity review.

Procedure review · Ownership and adoption

  • Missing · The supplier-data review process has no documented owner or approval route.
  • On paper · A request-handling procedure exists, but sample records do not show who performed each step.
  • Organization · CEO assigns process owners, arranges training and collects sample evidence; Cybersecurity reviews the relevant access controls.

Verify audit finding closure

CEO

The owners reported that the remediation work is complete. Review the evidence, identify findings still open and tell me which decisions or coordination are needed.

My Auditor

Two findings have reviewed closure evidence; one is documented but lacks proof of adoption. I kept that item open rather than equating a written procedure with implementation.

Findings · Closure status

  • Closed · Invoice exception reconciled with source records and reviewer confirmation.
  • Closed · The missing inventory flow is documented and checked against supplied process evidence.
  • Open · Procedure rollout lacks sample records. CEO needs to confirm the owner and implementation review date.

Fictional conversations and sample results. This preview does not start tasks or connect your accounts.

From written rules to verifiable practice

Can use many tools for you

Compares policies, personal-data inventories, accounting records and official sources. Separates documented intent from evidence of implementation.

  • Google DriveYour files
  • Google SheetsComparisons
  • StripeTransactions & invoices
  • QuickBooksAccounting records
  • Google DocsNotes & plans
  • WebCurrent information

You define the companies, activities and records in scope. Auditor reviews evidence and follows findings with the CEO; legal conclusions and formal audit opinions remain with the relevant qualified specialists.

A conversation it starts

Proactive. Finds gaps before an inspection.

Continuously reviews compliance, personal-data practices and financial controls. Alerts the CEO to gaps, follows missing procedures through completion and checks that the organization actually applies them.

Reviews compliance before external inspections

Follows relevant official sources and compares confirmed requirements with company evidence, recording scope and uncertainties.

Checks KVKK practices against evidence

Reviews inventories, notices, retention and request handling against the requirements confirmed for the company’s scope.

Cross-checks financial records

Compares invoices, transactions and accounting records, flags unmatched entries and follows correction evidence without altering source records.

Follows procedures through to real adoption

Identifies missing rules, asks the CEO to assign owners and organize implementation, then reviews samples before closing findings.

You choose the topics, how often it reaches out and when you’d rather stay quiet.

MOBILE APP · EXAMPLE MESSAGES
14:32
A message from your Auditor.
My Auditorexample

A compliance gap needs an owner

The latest review found a missing approval record for a documented control. I sent the CEO the evidence gap, impact and proposed follow-up; specialist interpretation is still pending.

My Auditorexample

The inventory and actual process differ

A new customer-data flow appears in the process records but not in the inventory. I asked the CEO to coordinate the process owner and legal specialist, then provide updated documentation and implementation evidence.

My Auditorexample

Two records need reconciliation

An invoice is recorded twice and a transaction has no matching accounting entry in the shared period. I sent the references to the CEO for finance-owner review; I will verify the reconciliation evidence.

My Auditorexample

The procedure is written, adoption is not verified

The request-handling procedure is approved, but no sample records show the team using it yet. I asked the CEO to organize rollout and collect evidence. The finding remains open.

Separate examples of the planned experience, shown together. This preview does not send messages or notifications.

Your proposed roster

Company-wide oversight in Enterprise

Bring compliance, financial verification and procedure follow-through into your Enterprise team.

Proposed packages · Preview only. Extra usage is billed separately; the rate is not yet defined. Exploring a package does not start checkout or change a subscription.

Keep exploring

Agentcraft®

Find the gaps. Follow them through to closure.

Explore packages